


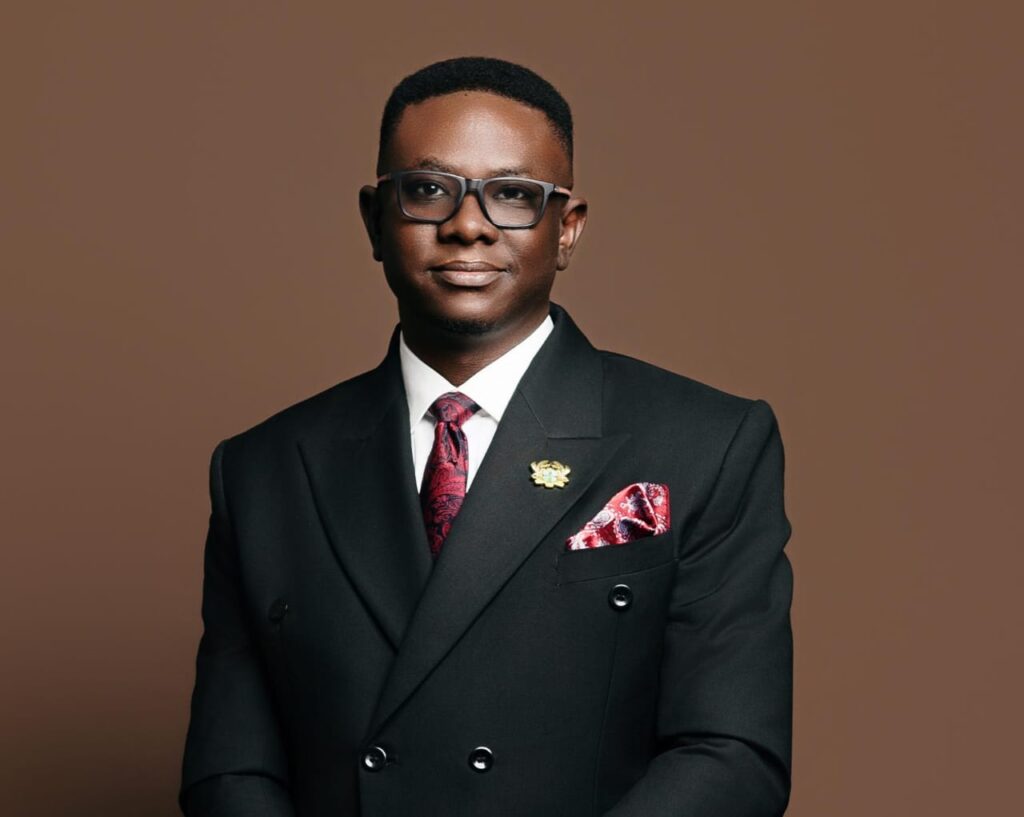
The National Housing Fund (NHF) has reduced the interest rate under its National Mortgage Scheme from 13.5 per cent to 8.4 per cent, opening up opportunities for prospective homeowners who previously struggled to qualify for financing.
The Fund’s Chief Executive Officer, Prosper Hoetu, announced this at the opening of the National Conference on Housing Finance at the Mövenpick Ambassador Hotel in Accra on Wednesday, 7 October 2026.
He said lending under the scheme resumed in September 2026, following a review aimed at making housing finance more affordable and accessible. Financing for developers is now available at an interest rate of 10.4 per cent.
“Last month, the Fund resumed lending under the National Mortgage Scheme at an interest rate of 8.4 percent, down from 13.5 percent. Developer financing is now at 10.4 percent,” he said.
Mr Hoetu attributed the revised rates to prudent economic management and a blended financing arrangement between the NHF and its partner financial institutions.
He said the response had been encouraging, with the Fund receiving a significant number of applications and additional financial institutions expressing interest in participating.
“We therefore have to increase our investment in the Scheme to expand the programme and accommodate more applicants,” he added.
A financing system that leaves many behind
Mr Hoetu said Ghana’s housing challenge extended beyond the availability of houses to the difficulty many people faced in accessing suitable financing.
He illustrated the problem through three stories: a civil servant who retired after 35 years without completing his home; a market trader whose lack of conventional financial records hindered her access to a mortgage; and a young worker forced to live in a kiosk because he could not afford decent accommodation.
“For many Ghanaians, the difficulty is not that they do not want to own a house. It is rather the system does not always give them a realistic way of getting there,” he said.
Citing the 2024 Housing Profile, Mr Hoetu said people facing circumstances similar to those of the civil servant and trader accounted for about 60 per cent of Ghanaians who needed financial assistance to own homes.
He said Ghana’s mortgage penetration was estimated at just 0.3 per cent of Gross Domestic Product, placing it among the lowest in Africa.
About 90 per cent of housing delivery, he added, depended on people financing construction incrementally, with houses taking an average of ten years to complete. The formal real estate sector met only about 10 per cent of the country’s housing needs.
“These figures tell us that the housing problem is, to a large extent, also a financing problem,” he said.
More pathways to owning a home
Mr Hoetu called for housing finance arrangements that recognised the different circumstances of salaried workers, informal sector earners and young people.
He said lower-interest mortgages and rent-to-own arrangements could help workers acquire homes, while conventional requirements such as payslips and banking records risked excluding many people earning a living in the informal sector.
He also raised the possibility of allowing workers to use part of their pension contributions to support homeownership.
“He could also potentially use part of his pension contribution to support his homeownership dream. After all, what is the value of contributing towards retirement throughout one’s working life if, at retirement, one still does not have a home?” he asked, referring to the civil servant’s story.
The proposal was presented as a potential option rather than an announced change to pension rules.
Mr Hoetu said the NHF had successfully piloted the National Mortgage Scheme and the Rent-to-Own Scheme, reviewing both over the past year and a half to improve affordability and access.
“What we need is a housing finance system that recognises the different circumstances of Ghanaians and provides multiple pathways to homeownership,” he said.
“For some, rent-to-own may be the appropriate pathway. For others, a mortgage will work. For others still, social housing will be necessary.”
New platform to connect housing demand and supply
The NHF has also facilitated the development of a homebuyers database intended to provide real-time information on housing demand and supply in Ghana.
Mr Hoetu said the platform would be showcased at the conference, allowing stakeholders to offer feedback on how it could be improved.
The two-day conference brings together Ghanaian and international experts to examine access to housing finance, constraints on supply, climate-smart construction, non-interest banking and green financing.
He also announced the completion of a rapid diagnostic assessment commissioned in August 2026 with Shelter Afrique Development Bank and the Ministry of Works, Housing and Water Resources.
The assessment used Shelter Afrique’s VIRAL Diagnostic Toolkit, which examines vision, institutions, regulations, actors and local initiatives within the housing sector.
Its findings are expected to inform a proposed Country Housing and Urban Development Partnership Strategy to guide resource mobilisation and investment.
Mr Hoetu stressed that improving housing finance could also generate wider economic benefits through construction jobs, demand for building materials and professional services, and increased business for financial institutions.
“If people cannot access affordable finance, they cannot buy homes. Developers also struggle to sell what they build. Capital remains tied up, and the housing sector cannot reach its full potential,” he said.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
Source link


