


Investor sentiment towards banking stocks is expected to remain positive, supported by dividend payouts across most listed banks.
According to the Databank Research 2026 Half-Year Outlook, the resumption of dividend payments, following regulatory approval, reflects significantly stronger capital buffers, strong profitability despite lower interest rates, with sector net income growth of about 4% between first-halves of 2025 and 2026.
Additionally, there is enhanced asset quality, signaling the sector’s continued recovery from the effects of the Domestic Debt Exchange Programme (DDEP).
The report stated that although non-performing loan (NPL) ratios remain above the Bank of Ghana’s regulatory threshold for some banks, it expects asset quality to improve further as credit conditions normalise and recovery efforts gain momentum through the remainder of the year.
The sector’s Non-Performing Loans (NPLs) declined to 16.1% in half-year 2026 from 23.1% in half-year 2025, reflecting early signs of balance sheet repair.
“We expect banks to intensify loan recovery initiatives and work towards the central bank’s 10% regulatory threshold by year-end, in line with the stipulated deadline”, Databank Research explained.
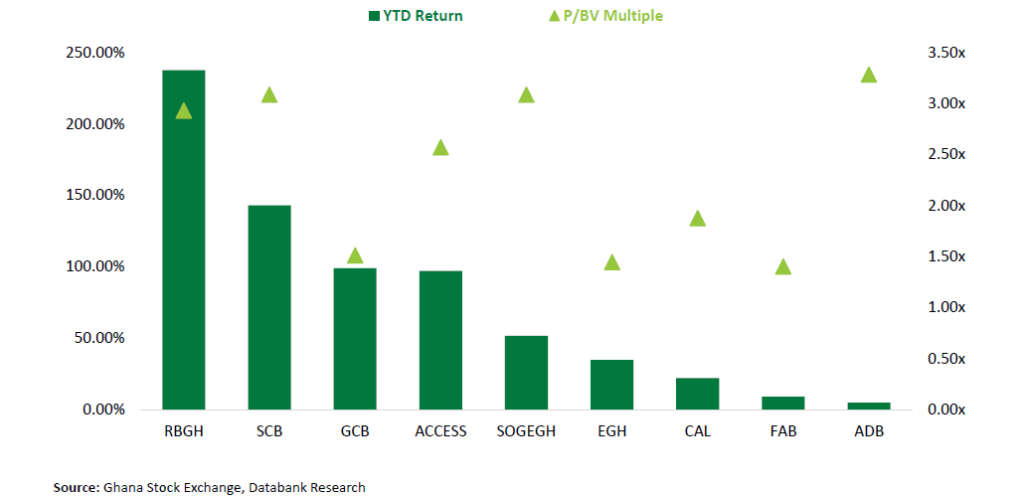
It added that the capital adequacy has also strengthened across the sector, rising to 20.4% in half-year 2026 from 19.7% in half-year 2025, underscoring a more resilient banking system with stronger capacity to absorb potential macroeconomic and credit shocks.
It continued that its analysis favour banks with strong capital positions, improving asset quality and resilient profitability.
“Although lower interest rates may compress net interest margins over 2H’26 [Second-half year 2026], we expect disciplined loan growth, and growing credit demand will support earnings momentum. In our view, improving macro conditions, stronger earnings visibility and dividend resumption suggest further upside through 2H’26.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
Source link
