


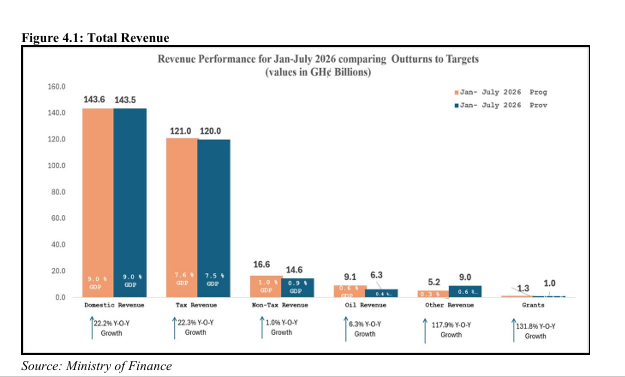
The Total Revenue and Grants in the first seven months of 2026 amounted to GH¢144.571 billion, about 9.1% of Gross Domestic Product (GDP).
This is lower than the target of GH¢144.951 billion (9.1% of GDP).
According to the September 2026 Monetary Policy Report, domestic revenue totalled GH¢143.522 billion (9.0% of GDP) in July 2026, below the target of GH¢143,630.9 million (9.0% of GDP).
The report alluded that the revenue outcomes reflected marginal underperformance of tax revenue, oil revenue, as well as grants.
Tax Revenue (comprising taxes on income and property, taxes on domestic goods and services, international trade taxes, and oil and gas related taxes) amounted to GH¢120.008 billion (7.5% of GDP), lower than the target of GH¢121.033 billion (7.6% of GDP).
This represented a negative deviation of 0.8% from the target.
Non-Tax Revenue totalled GH¢14.562 billion, below the target of GH¢16.590 billion by 12.2%.
Compared with the outturn for 2025, this translates into a year-on-year growth of 1.0%.
According to the report, this performance was mainly due to lower-than-programmed Dividend/Interest and Profits from Oil (CAPI) as well as the Yield from Capping Policy for the collection period.
Oil Revenue amounted to GH¢6.290 billion, lower than the target of GH¢9.064 billion by 30.6%.
This tax type also recorded a year-on-year growth of 6.3%.
Other Revenue amounted to GH¢8.950 billion, above its target of GH¢5.174 billion, representing an overperformance by 73%. This outturn was 117.9% above GH¢4.106 billion collected in the corresponding period of 2025.
Grants received for January-July 2026 totalled GH¢1.049 billion, a shortfall of 20.5% from the programmed target of GH¢1.320 billion. This outturn was also higher than GH¢452.7 million received in the corresponding period of 2025, translating into a year-on-year growth of 131.8%.

Drivers of Revenue Performance
Corporate income tax was 21.7% above target, which could be attributed to higher payments by major mining companies due to the increase in the average price of gold and growth in revenue from the banking sector.
According to the report, there was also an increase in mineral royalties, which was due to the increase in the average gold price above the US$4,000 per fine ounce threshold, triggering the application of a higher mineral royalty rate for taxpayers.
However, the expected revenue from the import sector fell short of target due to undershooting of CIF targets for the period.
Also, petroleum sector revenue was below target.
There was a shortfall in grants, which reflected in delays in project disbursements from development partners.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
DISCLAIMER: The Views, Comments, Opinions, Contributions and Statements made by Readers and Contributors on this platform do not necessarily represent the views or policy of Multimedia Group Limited.
Source link


